Yes, a non-resident can be appointed as a director of a UK company, but the appointment itself can trigger UK PAYE, National Insurance and identity verification duties the moment any boardroom duties are carried out here. The scale of the obligation depends on how many UK workdays the director clocks up and how their fee is structured. Practical next steps are straightforward: verify identity with Companies House, track UK workdays, and pick a payroll method before the first payment goes out.
TL;DR:
- From November 18, 2025, every director and person with significant control must verify identity; missing personal codes block confirmation statement filings.
- Fees for UK duties remain taxable despite overseas residence; section 690 or a GME notification can limit PAYE to the UK share.
- HMRC’s NIC concession generally covers no more than ten board meetings yearly and two nights per visit, and excludes operational or consultancy work.
- Travel and subsistence may be tax free at temporary workplaces, but attendance above 40% or beyond 24 months can make those costs taxable.
- With shadow payroll, employer paid UK tax can become a taxable benefit, so companies must reconcile overseas and UK payroll figures carefully.
Table of Contents
- Can a non-UK resident be a director? Companies House verification and appointment mechanics
- Tax and PAYE: when directorship pay is treated as UK-source and employer obligations
- National Insurance: the NIC concession, reciprocal coverage and employer registration consequences
- Expenses and workplace status: when travel and subsistence are taxable
- Practical compliance checklist: what companies must do now
- Common pitfalls and when to involve a specialist adviser
- Legal responsibilities and fiduciary duties of a non-resident director under UK law
- Implications of non-resident directorship on company statutory compliance and reporting
- Visa and immigration considerations specific to non-resident directors working in the UK
- Author perspective from Price & Accountants on handling NRD compliance
- How Price & Accountants can help with director payroll and compliance
- FAQ
- Sources
Can a non-UK resident be a director? Companies House verification and appointment mechanics
There is no residency requirement to hold a UK directorship. A company can appoint someone who has never set foot in the country, and many fast-growing tech firms do exactly that when a founder or investor sits abroad.
What has changed is the paperwork around identity. From 18 November 2025, every director and every person with significant control must verify their identity with Companies House and obtain a personal verification code. That code has to be linked to the individual’s appointment and quoted on the company’s confirmation statement.
Missing codes are not a minor administrative gap: they stop a confirmation statement from being filed at all, which is an offence for the company and its officers.
Practical steps for getting this done:
- Ask new and existing non-resident directors to complete verification through GOV.UK One Login as soon as the appointment is confirmed.
- Where a director cannot use One Login easily from overseas, an Authorised Corporate Service Provider can verify identity on their behalf.
- Keep a simple log of who has verified, when, and which code belongs to which appointment, since this will be needed at every confirmation statement filing. Our guide on appointing a UK director within 14 days of the ID checks walks through the filing sequence in more detail.
Tax and PAYE: when directorship pay is treated as UK-source and employer obligations
HMRC’s starting position is that a director’s fee relating to work carried out in the UK is UK-source income, whatever the director’s own tax residence. Double tax treaties rarely change this outcome: HMRC’s own manual confirms that the short-term business visitor exemption, which shelters many employees from UK tax on brief visits, is specifically excluded for directors’ fees. Most treaties contain a dedicated directors’ fees article that lets the company’s home country, the UK in this case, tax the fee regardless of where the director lives.
Employers then face a choice on how to withhold:
- Operate PAYE on the full fee as the default position, which is simplest but can over-withhold where only a fraction of duties relate to the UK.
- Apply for a section 690 direction or submit a globally mobile employees (GME) notification, both of which let the company report and tax only the apportioned UK element of earnings.
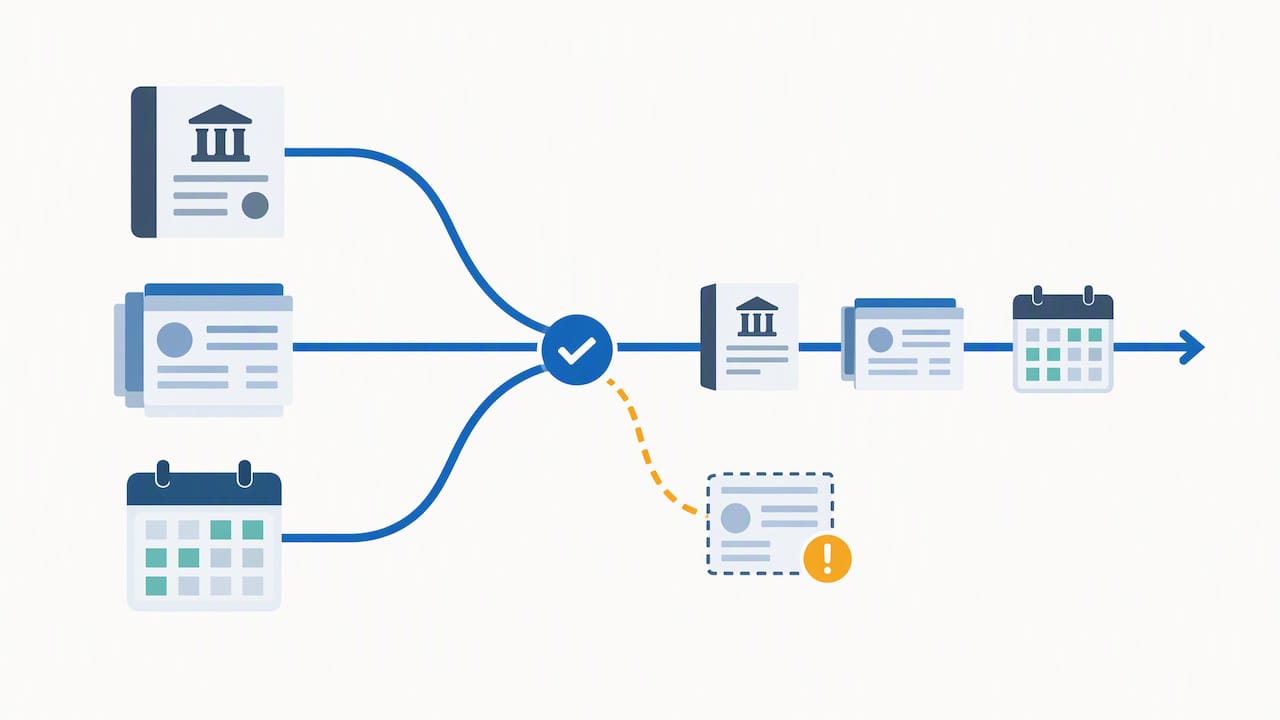
- Set up a shadow payroll where the director is actually paid from an overseas payroll, reporting the UK tax liability without a real UK payment running alongside it.
Shadow payrolls carry their own trap: when UK tax is settled on the director’s behalf rather than deducted from pay, that settlement can itself become a taxable benefit, so the figures need reconciling carefully between the two payrolls, as industry guidance on non-resident director compliance sets out.
On the director’s side, a non-resident who has UK tax withheld, whether under full PAYE, a section 690 apportionment or shadow payroll, usually still needs to report the income through self-assessment and may claim credit relief at home where a treaty allows it.
National Insurance: the NIC concession, reciprocal coverage and employer registration consequences
Class 1 National Insurance can apply whenever a director performs duties in the UK, separately from income tax. The main escape routes are an A1 certificate confirming continued coverage under EEA social security rules, a reciprocal agreement with the director’s home country, or HMRC’s own administrative concession for infrequent attenders.
That concession, set out in HMRC’s National Insurance manual, only covers directors who come to the UK purely to attend board meetings, and it is tightly bounded:
- Visits are generally limited to no more than ten board meetings per tax year.
- Each visit should last no more than two nights.
- The concession covers board attendance only, not wider operational or consultancy work carried out while in the country.
Breach any of those limits, even by one extra night on one trip, and the concession falls away, leaving the company exposed to employer NIC on the full fee.
Pro Tip: Log every UK visit date, purpose and duration for each non-resident director as it happens, rather than reconstructing it later when HMRC asks.
Where the concession does not apply and no A1 or reciprocal cover exists, the company may need to register as a foreign employer operating PAYE and NIC from abroad, and should keep documentary proof of any overseas social security coverage to hand.
Expenses and workplace status: when travel and subsistence are taxable
Whether a non-resident director’s flights, hotels and meals are tax-free depends on whether the UK counts as a temporary or permanent workplace for them. A temporary workplace, broadly one attended for a limited period or for no more than 40% of working time over a stretch expected to last under 24 months, allows travel and subsistence to be reimbursed free of tax. Once attendance becomes regular enough to cross those thresholds, the UK becomes a permanent workplace and the same costs become taxable.
Some qualifying non-domiciled directors can access a further five-year relief under Section 373, which keeps home-to-UK travel costs free of tax for a defined window even where the usual temporary workplace test might otherwise fail.
Recordkeeping matters more than the policy itself:
- Keep boarding passes, invoices and meeting schedules as evidence of each UK visit.
- Reconcile workday counts against the 24-month and 40% tests at least annually, not just when a query arises.
- Decide whether reimbursed costs sit on a P11D or are better bundled into a PAYE Settlement Agreement, since the right answer changes the reporting burden on both sides.
Practical compliance checklist: what companies must do now
Getting a non-resident director’s affairs in order comes down to a short sequence of decisions, taken early rather than retrofitted after HMRC asks questions.
- Verify every director’s identity with Companies House and record the personal code against their appointment.
- Choose a payroll route: full PAYE withholding, a section 690 direction or GME notification for apportioned reporting, or a shadow payroll where an overseas entity pays the director directly.
- Register as a UK or foreign employer as the chosen route requires, and set up the mechanics before the first payment rather than after.
- Check the director’s social security position, securing an A1 certificate or reciprocal cover confirmation, or testing eligibility for the NIC concession.
- Keep a running log of UK workdays, board meeting dates and travel evidence, and consider a PAYE Settlement Agreement for reimbursed expenses.
Pro Tip: Treat the first board meeting after appointment as the deadline for having payroll and verification sorted, not the first payday.
Companies paying from an overseas entity should also read our note on UK payroll and compliance for overseas founders before setting up the payment route.
Common pitfalls and when to involve a specialist adviser
The two most frequent failures are not operating PAYE at all on a director’s UK-related earnings, and misclassifying travel or subsistence that should have gone through PAYE as tax-free expenses. Because HMRC employer compliance checks can look back several tax years, both mistakes tend to surface as a liability covering multiple years rather than a single payment.
The NIC concession is the other recurring trip-wire: it reads as generous on paper but is lost the moment visit numbers or lengths creep past the stated limits, often without anyone noticing until a review.
- A section 690 direction or GME notification involves judgement calls on apportionment that are easy to get wrong without experience.
- Shadow payroll reconciliation between two jurisdictions’ tax years rarely matches up cleanly on a first attempt.
- Cross-border NIC and A1 queries often need direct correspondence with HMRC or an overseas authority, which takes longer than most companies expect.
Where fees or visit frequency are material, bringing in specialist support before the first payroll run tends to be far cheaper than unwinding a multi-year liability afterwards.
Legal responsibilities and fiduciary duties of a non-resident director under UK law
A director’s statutory duties under the Companies Act 2006 apply in full regardless of where that director lives. Living outside the UK does not dilute the duty to act within powers, to promote the success of the company, to exercise independent judgement, to avoid conflicts of interest, or to exercise reasonable care, skill and diligence.
In practice this means a non-resident director is expected to engage properly with board papers, attend meetings (in person or remotely) with enough preparation to contribute meaningfully, and understand the company’s financial position well enough to spot problems. Distance from the UK does not excuse ignorance of statutory filing deadlines, wrongful trading risk if the company becomes insolvent, or disqualification proceedings if duties are neglected.
Fiduciary exposure tends to bite hardest where a non-resident director is appointed as a figurehead, with day-to-day decisions left entirely to UK-based colleagues. That arrangement does not reduce legal liability: Companies House and the courts treat the appointment as real, with real duties attached, whether or not the director is actively involved. Boards that appoint overseas directors for investor relations, SEIS and EIS compliance oversight, or international credibility should build in enough reporting and briefing to let that director genuinely discharge their duties rather than simply lending a name to the register.

Implications of non-resident directorship on company statutory compliance and reporting
Appointing a director based overseas changes very little about the company’s own filing obligations: annual accounts, confirmation statements and corporation tax returns are still due on the same schedule. What changes is the administrative load behind those filings.
Confirmation statements now depend on every director’s Companies House identity verification being complete and their code correctly referenced, so a single unverified overseas appointee can hold up the entire filing. Companies with a mix of resident and non-resident directors often find the non-resident cases take longer to resolve simply because remote identity checks and document gathering take more coordination.
There is a secondary compliance layer worth watching: HMRC increasingly cross-references Companies House appointment records against payroll filings, so a director who appears on the public register but never shows up on a payroll or a section 690 notification is a mismatch that can prompt a compliance check. Keeping Companies House records, payroll registrations and workday logs consistent with each other is now as much a part of statutory compliance as the filings themselves.
Visa and immigration considerations specific to non-resident directors working in the UK
Being a company director and having the right to work in the UK are separate questions, and conflating them causes real problems. A non-resident can hold a UK directorship without ever needing a visa, provided their role is limited to governance activities such as attending board meetings, reviewing accounts and signing statutory documents from abroad or on short visits.
Difficulties arise when a non-resident director starts doing operational work while physically in the UK: managing staff, running day-to-day business functions, or spending extended periods in the country. At that point, ordinary visitor rules may no longer cover the activity, and the company should check whether a sponsored work route or another visa category is needed before the director’s role expands.
Short board-meeting visits generally sit comfortably within standard visitor rules, but a director who starts combining board attendance with consultancy, operational decision-making or client-facing work on the same trips should have their visa position reviewed separately from their tax and NIC position, since immigration status and tax residence are assessed under entirely different rules.
Author perspective from Price & Accountants on handling NRD compliance
Experience with international founders shows that payroll and verification often get treated as paperwork to tidy up later, when they are actually the first decisions that need making. Sorting identity verification, payroll method and NIC position before the first payment runs is far simpler than untangling several years of underpaid tax after an HMRC review.
— Rahamut
How Price & Accountants can help with director payroll and compliance
Getting a non-resident director’s payroll, NIC position and Companies House filings aligned from day one saves far more time than fixing them retrospectively. Payroll and pension administration services can cover shadow payroll calculations and section 690 reporting, and finance directorship support can help with setting up international entities without tripping over employer registration.
If a non-resident appointment is coming up, get in touch to review director payroll exposure and the Companies House verification logistics before the first board meeting. Our services overview sets out the full range of payroll, advisory and international setup support available, and identity checks carried out through a platform like Finchecker’s sanctions and KYC screening can sit alongside Companies House verification for groups with wider onboarding needs.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can a foreigner be a director of a UK company?
Yes, there is no residency requirement to be a UK company director, and a foreign national can be appointed regardless of where they live. From 18 November 2025 they must still verify their identity with Companies House and obtain a personal code for their appointment.
Do non-resident directors pay UK tax on their director’s fees?
Director’s fees relating to duties performed in the UK are generally treated as UK-source income and taxable here, even where the director lives abroad. Double tax treaties rarely remove this because the short-term business visitor exemption is specifically excluded for directors’ fees.
Does National Insurance apply to non-resident directors?
Class 1 NICs can apply once a director performs duties in the UK, unless an A1 certificate, a reciprocal social security agreement, or HMRC’s limited concession for infrequent board attendance applies. That concession is narrow and is lost if visit frequency or length goes beyond the stated limits, as described in HMRC’s internal guidance.
What is a section 690 direction and when is it needed?
A section 690 direction lets an employer apply PAYE to an apportioned share of a globally mobile director’s earnings rather than withholding on the full amount by default. Companies can request this or use the related globally mobile employees notification where a director splits their time between the UK and another country.
How does Companies House identity verification affect existing non-resident directors?
Existing directors, not just new appointees, must complete identity verification and link their personal code to their role. Missing codes block the company’s confirmation statement filing, which is why building verification into routine company administration matters for every non-resident director already on the register.
Sources
Recommended
- UK startup payroll obligations: a clear founder’s guide
- UK Payroll, VAT & Compliance for US Companies: What Overseas Founders Need to Know Before Hiring in the UK
- UK company setup steps: a founder’s 2026 guide
- UK Payroll for Foreign Employers: How US Companies Hire UK Staff Without Compliance Headaches